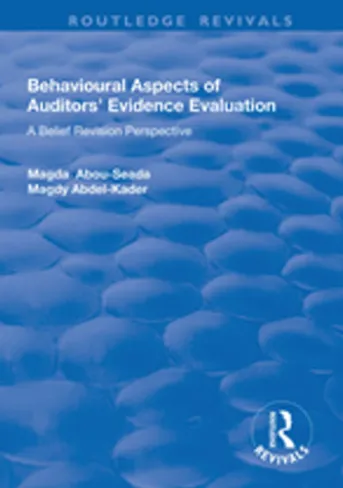
Behavioural Aspects of Auditors’ Evidence Evaluation
€10.23
This title was first published in 2003. Based on psychological research, auditing studies have focused on ‘belief revision’ as a way of understanding how auditors evaluate evidence. Moreover a belief revision process is consistent with US auditing standards. UK standards on the other hand do not appear to give guidance on the process to follow when evaluating evidence. Research in the US indicates that auditors do in fact follow a belief revision process in accordance with US standards. Employing survey research (based on personal interviews with a number of experienced UK auditors) this book demonstrates how auditors prefer to be described as following the open mind approach. Building on the findings of the interviews the book then describes an experimental study to investigate the differences between the belief revision and open mind approaches in terms of their effect on the efficiency and effectiveness of the audit process. The book concludes that the belief revision approach would improve the efficiency of the audit process without affecting its effectiveness or outcomes.
Over dit boek
Be the first to review “Behavioural Aspects of Auditors’ Evidence Evaluation”
Related products
Boekhouden
Biografieën
Business & Financiën
Branchen & Beroepen
Business & Financiën
Business & Financiën
Business & Financiën
Business & Financiën
Biografieën
Business & Financiën
Boekhouden
Business & Financiën
Business & Financiën
Business & Financiën
Business & Financiën
Reviews
There are no reviews yet.